

AI Summary
- OMFIF presents programmable digital money as potential settlement infrastructure for AI initiated commerce.
- Hedera receives a concrete role in the report through cryptographic audit records for AI operations.
- Tokenized deposits, stablecoins and CBDCs still require legal certainty, interoperability and clear liability rules.
- References to Ripple, XRP, Quant Network and Chainlink vary in strength and should not be treated as equivalent adoption evidence.
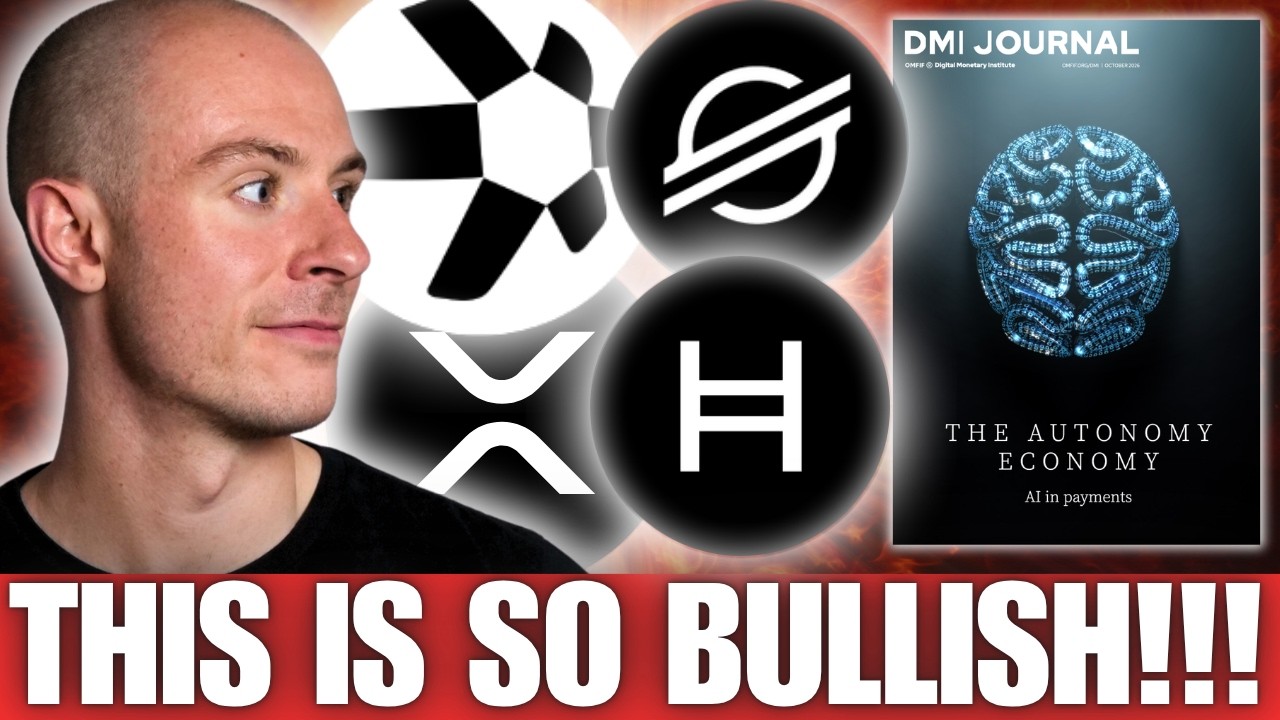
The popular narrative around autonomous commerce is that artificial intelligence will simply create another wave of crypto adoption. The concrete development is narrower and more consequential: OMFIF, an independent think tank focused on central banking, economic policy and public investment, has placed digital money and distributed infrastructure inside its analysis of machine initiated payments.
The report, titled The Autonomy Economy: AI in Payments, identifies auditability, authorization, settlement and liability as core requirements. Hedera receives a specific technical role through verifiable AI operations anchored to its network. References to tokenized bank money also intersect with work associated with Quant Network, while the cases for Ripple, XRP and Chainlink require a more qualified reading.
AI payments turn authorization into an infrastructure problem
AI agents can already assist users by finding products, comparing offers and recommending purchases. Giving an agent authority to complete transactions without intermediate human supervision creates a different risk profile. Payment execution becomes inseparable from questions about who granted permission, what limits applied and who bears responsibility when the result is fraudulent or incorrect.
The concerns attributed to the Bank of England in the report are familiar to financial regulators but harder to resolve when software can initiate multiple transactions across different systems. Consent must remain demonstrable, disputes need a defined process, and competing protocols must not produce fragmented commercial networks.
- Authorization: A payment system must establish what an agent was permitted to do.
- Authentication: Merchants and financial institutions need confidence in the identity behind an automated request.
- Liability: Rules must assign responsibility for erroneous or fraudulent transactions.
- Interoperability: Agents must communicate across payment systems without depending on isolated walled gardens.
These constraints explain why agentic payments are not merely an AI software story. They are also a financial infrastructure problem involving identity, policy enforcement, final settlement and evidence that can survive an audit.
Hedera is positioned as an audit layer for AI agents
The clearest protocol specific example concerns Hedera. The report describes a system in which cryptographic certificates are generated for AI operations, rooted in supported hardware and anchored immutably on the Hedera network. The source connects this approach with Nvidia and Intel silicon, Equity Labs, Accenture and Hedera.
Knowing who authorized an agent matters, but so does being able to prove exactly what it did.
This is a stronger claim than a general reference to blockchain. It gives the network a defined function: preserving tamper resistant evidence about an AI operation. The source further states that verifiable compute has been deployed for government oversight of agentic systems in public safety and critical infrastructure.
Our analysis is that this supports an infrastructure thesis for Hedera, but not an automatic valuation conclusion for HBAR. A network can be technically relevant without every deployment producing material token demand. The critical questions are whether the process reaches production scale, which operations are written to the network and how fees or token usage develop.
- Identity evidence: The system needs to show who authorized an AI agent.
- Execution evidence: Cryptographic records can document what the agent actually did.
- Hardware roots: The described model connects verification with supported silicon.
- Ledger anchoring: Hedera supplies an immutable record for the resulting certificates.
This use case is consistent with AllinCrypto’s earlier examination of Hedera’s verifiable AI case for agentic commerce and its developing AI trust layer around Nvidia agent safety.
Tokenized bank money could become the control surface
The report treats tokenized bank money as potential compliant infrastructure for autonomous commerce. This matters because AI initiated transactions need more than a low cost transfer rail. They also need embedded conditions, predictable redemption, legal enforceability and controls compatible with regulated institutions.
Digital money pilots show that tokenized settlements can support automated conditional workflows and in some designs expand operating hours.
Quant Network is relevant through its work on interoperability for tokenized deposits. The supplied context includes The Clearing House selecting Quant for a tokenized deposit network, as well as Quant connecting UK and US bank rails to tokenized deposits. These developments support a role for Quant infrastructure, although they do not establish that every system considered in the OMFIF report runs on QNT or a public blockchain.
- Programmability: Payments can execute when agreed conditions are satisfied.
- Control: Regulated money can retain institutional rules and compliance requirements.
- Settlement: Digital money can provide the payment leg for an AI generated decision.
- Redemption: Private digital money needs credible conversion at par.
Stablecoins and CBDCs face the same trust threshold
The report groups stablecoins, tokenized deposits and CBDCs as possible settlement layers rather than treating them only as competing monetary products. Their common purpose would be to turn an agent’s instruction into an enforceable and auditable transfer.
Stable coins, tokenized deposits, and CBDC’s should be assessed less as isolated innovations and more as settlement layers for AI mediation payments.
The distinction is important. Fast or inexpensive settlement does not resolve privacy, legal status, operational resilience or liability. The report’s framework indicates that digital money can move from controlled tests toward trustworthy economic activity only when those surrounding conditions are credible.
- Legal certainty: Participants need confidence that an AI initiated transfer is enforceable.
- Privacy preserving compliance: Automated systems must meet regulatory requirements without exposing unnecessary information.
- Resilience: Payment availability must withstand technical and operational failures.
- Clear liability: Users and providers need rules for failures, fraud and unauthorized activity.
Ripple, XRP and Chainlink need a narrower interpretation
The source material includes industry references to Ripple’s enterprise treasury and stablecoin work. That supports Ripple as a participant in the wider digital money environment, but it does not by itself prove that XRP is a designated settlement asset for OMFIF’s agentic economy framework. Our view is that the corporate reference and the token thesis must remain separate unless a primary implementation explicitly connects them.
The same discipline applies to Chainlink and LINK. Project Guardian is cited as an example of work involving tokenized assets, tokenized money, delivery versus payment, standards and risk management. The supplied source associates Chainlink with that broader initiative, but does not establish an exclusive role for the network in AI powered settlement.
AllinCrypto has separately examined how Ripple’s payment and treasury expansion affects the XRP utility thesis. That context is relevant, but it remains different from direct evidence that AI agents will use XRP for settlement.
What this means
Auditability may be the first durable blockchain role. Hedera’s clearest position is not as a generic payment coin but as a record layer for cryptographic evidence about AI operations.
Regulated money and interoperability are complementary. Tokenized bank money can carry institutional controls, while systems associated with Quant Network can help connect otherwise separate rails.
Protocol mentions are not equal to token adoption. References to HBAR, XRP, QNT or LINK should be tested against production usage, fee generation and explicit settlement design before drawing market conclusions.
We see the report as evidence that the infrastructure debate is becoming more precise. The central question is no longer whether machines can initiate payments. It is whether institutions can authorize, verify, settle and reverse those payments under rules that courts, regulators and customers can understand.
Bigger picture
The agentic payment thesis sits inside a broader shift toward programmable institutional money. Recent AllinCrypto coverage has tracked Quant’s tokenized deposit infrastructure beyond individual ledgers and the way Hedera AI trust intersects with Quant interoperability.
Those developments point toward a layered market rather than a single winning chain. Identity and audit records, regulated deposits, public or permissioned ledgers, instant payment systems and cross border messaging may coexist. An AI agent could select among these rails according to cost, liquidity, foreign exchange timing, finality, availability and customer preference.
The measured conclusion is therefore not that an autonomous crypto economy has already arrived. It is that financial institutions are defining the controls required before autonomous transactions can move beyond pilots. Hedera has a concrete place in that conversation, while the investment implications for its token and for other named assets remain conditional.
Sources
This article is for informational purposes only and does not constitute financial advice.