

AI Summary
- Hargreaves Lansdown is opening access to nine Bitcoin and Ethereum exchange traded notes for eligible investors on its advanced service.
- Stronger US payrolls increased expectations for tighter monetary policy, reinforcing the influence of interest rates, Treasury yields and the US dollar on crypto markets.
- BlackRock’s Robbie Mitchnick connected Bitcoin demand with concerns about sovereign debt, deficits and long term monetary debasement.
- Fidelity’s cautiously constructive bottom thesis remains conditional because historical crypto cycles are unreliable timing tools.
The common narrative is that crypto’s next phase will be determined primarily by adoption. The more immediate fact is that Bitcoin and Ethereum remain highly sensitive to conventional macroeconomic signals. Stronger reported US payrolls, changing expectations for Federal Reserve policy and a firmer US dollar all weighed on the market even as institutional access continued to broaden.
The clearest adoption development came from Hargreaves Lansdown. According to the supplied source, the UK investment platform is opening trading in nine Bitcoin and Ethereum exchange traded notes to approximately two million investors through its advanced investment service. That gives eligible clients another regulated route to gain BTC and ETH exposure without trading the underlying assets directly.
Our analysis is that these developments describe two forces operating at once. Distribution is improving through products such as crypto ETNs, while monetary conditions continue to govern short term risk appetite. This tension also complements our previous examination of how Bitcoin volatility responds to yields and the dollar.
Strong payrolls reset the interest rate debate
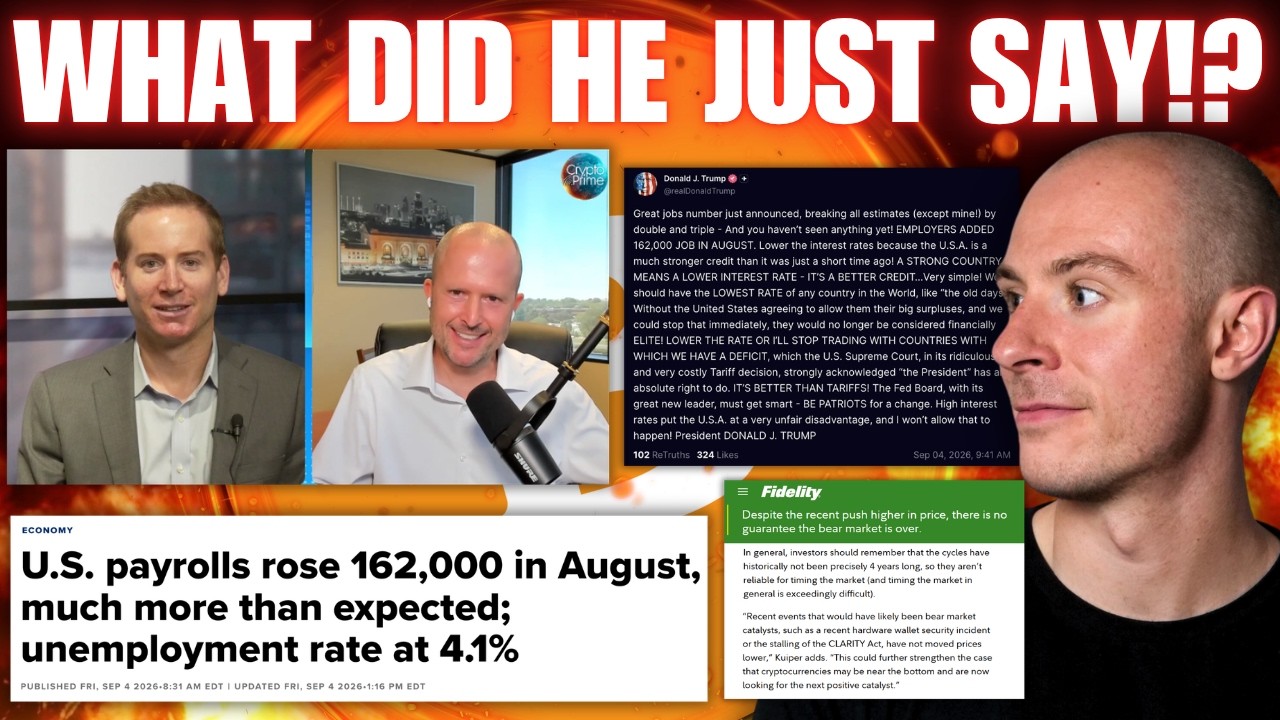
The supplied figures put August nonfarm payroll growth at 162,000, compared with a consensus estimate of 53,000, while unemployment remained at 4.1%. Those numbers have not been independently substantiated by an additional primary document in the supplied material, so they should be understood as figures reported by the source rather than as a separate AllinCrypto verification.
The immediate market logic was straightforward. A resilient labor market can give policymakers more room to maintain or tighten restrictive policy. The source reported that the implied probability of a rate increase had moved to 59%, approximately eight percentage points higher after the labor report. That is a market expectation, not a guarantee of a policy decision.
“Great jobs numbers just announced, breaking all estimates except mine by double and triple and you haven’t seen anything yet.”
That statement was attributed to President Donald Trump in the supplied transcript. His broader position favored lower interest rates, but the bond market mechanism can point in the opposite direction when economic data appear stronger than expected. Investors may anticipate tighter policy, sell longer dated government debt and demand higher yields. Political preference does not determine that repricing by itself.
- Labor signal: The reported payroll increase substantially exceeded the cited consensus.
- Policy signal: Strong employment data were interpreted as giving the Federal Reserve more scope to remain restrictive.
- Market signal: Yields and the dollar initially rose while crypto weakened, according to the source.
Why Bitcoin still trades through the macro channel
Bitcoin is often presented as an alternative monetary asset, but its short term trading behavior can still resemble that of a liquidity sensitive risk asset. When Treasury yields rise, investors can obtain a higher return from conventional instruments. When the US dollar strengthens, dollar denominated financial conditions also tend to tighten. Both developments can reduce the marginal appetite for volatile assets.
The source described a brief pattern in which yields and the dollar spiked before easing, while crypto moved in the opposite direction. The important question is not the intraday reversal but whether the underlying trend persists. A lasting combination of higher real borrowing costs and a stronger currency would be a headwind. A divergence in which yields rise but the dollar weakens could create a more complicated environment.
Inflation adds another layer. Bitcoin’s fixed supply narrative can attract demand when investors fear currency dilution, yet an inflation shock may initially bring tighter monetary policy and weaker risk appetite. In our view, the hedge thesis and the liquidity thesis can be valid over different horizons. Treating either one as an automatic price rule obscures that distinction.
BlackRock connects Bitcoin demand with sovereign debt concerns
BlackRock executive Robbie Mitchnick, identified in the source as the firm’s head of digital assets, linked the recent Bitcoin rally to growing attention on global debt, government deficits and the long end of sovereign bond markets. His distinctive claim was that concern about the sustainability of those systems is strengthening the appeal of assets associated with scarcity.
“If you look at the current market environment, a lot of the move that we’ve seen that 30% rally uh that you noted, Nate, a lot of that obviously has been driven as is well documented by a growing focus and concern over uh global debt and deficit levels um and what’s happened at the long end of of bond markets for governments uh around the world, which is really uh at its heart a concern over um you know sustainability and some of that and what the implications are for uh potential monetary debasement, money printing, etc. uh in the long run.”
This is an attributed interpretation rather than proof that debt concerns caused the entire move. Bitcoin demand can reflect several overlapping factors, including liquidity, product access, regulation and portfolio positioning. Still, the comparison with gold is analytically useful: both assets can attract buyers concerned about monetary debasement, even though their volatility, market structure and operating characteristics differ.
- Sovereign risk: Persistent deficits can increase concern about the long term management of public debt.
- Currency risk: Monetary expansion can strengthen demand for assets perceived as difficult to dilute.
- Access: Institutional products can convert that thesis into investable exposure for a broader group of clients.
Fidelity’s bottom thesis remains deliberately conditional
Comments attributed to Fidelity offered a cautiously constructive view of the crypto market while rejecting certainty. The core observation was that several negative catalysts had failed to push prices materially lower. The cited examples included hardware wallet security incidents and the stalling of the CLARITY Act.
“Despite the recent push higher in prices, there is no guarantee the bare market is over.”
The transcript uses the word “bare,” although the intended reference appears to be a bear market. The surrounding remarks also warned that historical cycles have not been precisely four years long and therefore should not be treated as reliable timing devices. That caution is more important than the proposed bottom itself.
A market that stops declining after negative news may be showing seller exhaustion, but resilience alone cannot confirm a durable reversal. New demand must still absorb supply, and macro conditions can change quickly. Regulatory progress could become a positive catalyst, although neither the outcome nor timing of congressional action is certain. Our earlier analysis of the interaction between US crypto policy and the dollar provides additional context for that unresolved tension.
Hargreaves Lansdown widens regulated ETN distribution
The most concrete institutional action in the source is Hargreaves Lansdown’s decision to offer crypto ETNs. The platform was reported to be making nine Bitcoin and Ethereum products available from September 3, with issuers including BlackRock, iShares, WisdomTree, 21Shares, Invesco, CoinShares and Bitwise. The transcript reported annual fees ranging from zero to 0.35%.
Access is not described as unrestricted. The products are intended for users of the platform’s advanced investment service. Investors must pass an appropriateness assessment and observe a 24 hour cooling off period before making their first trade. These safeguards underline that exchange traded access does not eliminate crypto market risk.
- Product scope: Nine ETNs providing exposure to Bitcoin or Ethereum.
- Investor reach: Approximately two million platform users were cited by the source.
- Eligibility controls: An appropriateness assessment and cooling off period apply.
- Economic exposure: Clients receive listed product exposure rather than direct ownership of BTC or ETH.
The shift is significant because Hargreaves Lansdown had previously resisted treating Bitcoin as an asset class, according to the source. A distribution decision does not necessarily imply institutional endorsement of Bitcoin’s valuation or monetary thesis. It does show that client demand, product availability and regulatory parameters can change what a traditional platform is prepared to offer.
What this means
1. Access is broadening faster than the macro risk is disappearing. New ETN distribution can support structural demand, but it does not insulate Bitcoin or Ethereum from changes in yields, the dollar or policy expectations.
2. Institutional narratives are becoming more specific. BlackRock’s debt and debasement argument presents Bitcoin as a response to sovereign monetary risk, while Hargreaves Lansdown’s action addresses the practical problem of how traditional investors obtain exposure.
3. A possible bottom is not a timing signal. Fidelity’s reported thesis is strongest as an observation about resilience. It remains insufficient on its own to establish that the market has entered a sustained advance.
We therefore see a constructive long term distribution trend alongside a mixed near term market setup. Investors weighing the adoption story should also examine monetary conditions, product structure and the possibility that policy expectations reverse again.
Bigger picture
Regulated ETN access belongs to a wider institutional shift, but the developments should not be collapsed into a single claim that all traditional finance activity is bullish for crypto prices. Our coverage of BlackRock and other institutions testing tokenized collateral concerns market infrastructure, whereas Hargreaves Lansdown’s action concerns investor distribution. They involve different products, networks and sources of demand.
Market flows can also diverge from the adoption narrative. The verified recent context includes an examination of crypto asset outflows alongside selective resilience. That distinction matters because institutional capability can expand even when aggregate positioning remains cautious.
The stronger conclusion is that crypto is becoming more connected to traditional finance on two fronts. Bitcoin and Ethereum are gaining additional investment channels, while their valuations remain exposed to the same rates, currencies and portfolio constraints that shape other global assets. For now, adoption and macroeconomics are complementary parts of the thesis rather than competing explanations.
Sources
This article is for informational purposes only and does not constitute financial advice.