

AI Summary
- Yen intervention may be weakening the US dollar without delivering the improvement in risk appetite that Bitcoin bulls would normally expect.
- Rising US two year yields indicate that monetary and inflation concerns remain active despite the softer dollar.
- The reported shift in open interest toward altcoins shows greater speculative participation, but it does not establish that a durable altcoin cycle has begun.
- Institutional adoption could broaden demand beyond Bitcoin over time, although the transcript provides no protocol level deployment evidence for that scenario.
- Our analysis remains cautiously constructive over the longer term while treating near term macro volatility as the dominant risk.
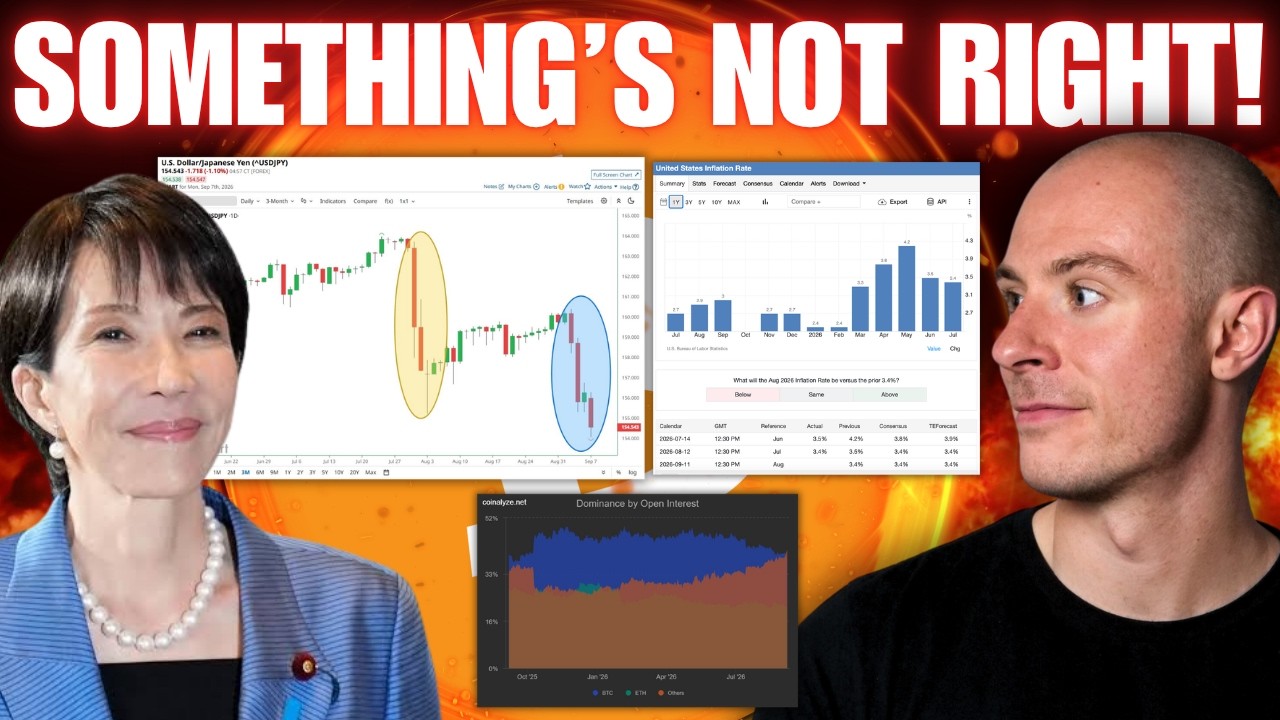
The familiar crypto playbook says a weaker US dollar should support Bitcoin and other risk assets. The present setup is less accommodating. The supplied market commentary reports substantial yen intervention and a falling dollar, yet it also observes firm US two year yields and little corresponding improvement in risk appetite.
That divergence is the central issue for the Bitcoin macro outlook. Currency intervention can move an exchange rate without resolving the inflation expectations, interest rate pressure or geopolitical uncertainty influencing wider markets. A weaker DXY therefore cannot be treated as an automatic green light for BTC.
At the same time, the source reports that altcoins have overtaken Bitcoin by their share of open interest. This is potentially important for market structure, but it is not proof of a new bull market. Our analysis separates that derivatives signal from the broader claim that Bitcoin can function as a dollar hedge.
Yen intervention complicates the dollar signal
The supplied commentary attributes recent dollar weakness to action intended to support the Japanese yen. It reports that Japan’s foreign reserves fell by a record $80 billion in August following intervention and that 27.1 trillion yen had been used during the year. These figures come from the transcript and are not accompanied by a primary document, so they should be treated as source reported rather than independently verified here.
The mechanism matters more than the headline direction of the dollar. Selling reserve assets and buying yen can pressure the dollar against the Japanese currency, but it does not necessarily produce easier financial conditions across every market. If the move is primarily intervention driven, Bitcoin traders cannot assume it carries the same information as dollar weakness caused by falling inflation or expectations of looser monetary policy.
- Currency effect: Yen purchases can weaken the dollar against the Japanese yen.
- Policy effect: Intervention alone does not settle the path of interest rates.
- Market effect: Crypto, equities and gold may fail to rally if investors still demand protection from inflation and geopolitical risk.
“I’m not buying this dollar weakness right now.”
That statement is a market opinion, not an established outcome. In our view, it is nevertheless a useful warning against reading one foreign exchange move in isolation. The duration, scale and effectiveness of intervention remain uncertain, and the transcript itself questions how long the policy can continue.
Rising two year yields create a macro divergence
The clearest challenge to the bullish dollar interpretation is the reported rise in US two year yields. Short maturity government yields are sensitive to expectations about monetary policy. When they rise while the dollar falls, the two signals may be describing different forces: intervention in foreign exchange and persistent rate pressure in fixed income.
Bitcoin has historically reacted to liquidity, real rate expectations and changes in risk appetite, but those relationships are neither fixed nor mechanical. The relevant question is not simply whether DXY is down. It is whether the combination of yields, inflation expectations and market positioning is becoming more supportive. The transcript’s answer is cautious because futures and crypto had not delivered the expected risk response.
“The only threat to the crypto market bottom being in is the dollar strengthens.”
This is a distinctive forecast from the source rather than an AllinCrypto conclusion. We see a broader range of risks. Even without sustained dollar appreciation, higher yields, leveraged positioning or an adverse inflation surprise could weigh on digital assets. Our related analysis of Bitcoin volatility across oil, yields and the dollar provides the closest internal context for that multi-variable framework.
- Bullish confirmation: A weaker dollar accompanied by falling yields and improving risk appetite would create a more coherent signal.
- Mixed evidence: A weaker dollar alongside rising yields suggests that intervention may be masking tighter conditions.
- Bearish confirmation: Renewed dollar strength combined with firm yields would increase pressure on leveraged crypto positions.
Inflation risk keeps monetary pressure alive
The source identifies CPI, oil and heating fuel as variables that could keep inflation pressure active. It also forecasts light crude oil futures reaching 105, but that is an attributed scenario rather than a verified price target. The transcript offers no underlying model for the forecast, so we do not adopt it as our base case.
The defensible point is narrower. If energy prices rise materially, markets may revise inflation and policy expectations. That could lift short term yields and reduce the appeal of assets whose valuations benefit from abundant liquidity. Conversely, a benign CPI result could weaken that chain of reasoning. Neither outcome is established by the source material.
“That’s my base case. I could be wrong.”
That uncertainty is appropriate. The scheduled inflation release is a potential catalyst, but one data point cannot confirm a lasting monetary shift. Our previous examination of Bitcoin’s inflation hedge thesis and global interest rates also shows why the asset’s response depends on how inflation affects yields and liquidity, not just on inflation itself.
Altcoin open interest challenges Bitcoin dominance
The transcript defines open interest as open positions and reports that altcoin open interest now exceeds Bitcoin open interest by dominance. In derivatives markets, open interest measures contracts that remain outstanding. It can reveal participation and leverage, but it does not by itself show whether traders are net bullish, whether positions are hedged or how vulnerable they are to liquidation.
“There are more open positions on altcoins now than there are Bitcoin.”
Because no underlying exchange list, methodology, timestamp or dataset is supplied, the reported ranking cannot support a precise market wide measurement here. It is best understood as a signal requiring confirmation. Aggregate figures can also conceal concentration in a small group of tokens or venues.
- What it can show: Growing derivatives participation outside Bitcoin.
- What it cannot show: Whether those positions are predominantly long or short.
- What needs confirmation: Venue coverage, asset composition, leverage and changes through time.
- Why it matters: Crowded positions can amplify both rallies and liquidations.
Our measured interpretation is that the signal may indicate greater speculative breadth, not that an altcoin season has been established. If yields remain restrictive or the dollar rebounds, leveraged altcoin exposure could prove more fragile than the same headline statistic initially suggests.
Institutional adoption is the longer term thesis
The longer term thesis links stronger altcoin participation to institutional adoption and the use of networks for financial infrastructure. DTCC is mentioned as an example of what could drive that transition, but the transcript provides no primary document or concrete deployment details. We therefore treat the connection between present open interest and future institutional use as a hypothesis.
There is still a coherent distinction behind it. Bitcoin’s principal institutional narrative can center on scarcity and an alternative store of value, while other networks may be evaluated for settlement, tokenization, data delivery or application execution. Those use cases can create different demand channels, but they do not ensure that each protocol’s token captures the resulting economic value.
“this could be a sign of what’s to come in potentially a more institutionally institutionally driven bull market.”
That forecast belongs to the source and remains uncertain. Verified internal context does show that institutional experimentation spans several networks. Examples include DTCC and tokenized assets on Stellar and Chainlink’s institutional runtime thesis. Those developments support studying protocol specific adoption, but they do not validate a general altcoin rally.
What this means
1. Dollar weakness needs confirmation. Yen intervention may explain the currency move without improving the inflation and rate backdrop. Bitcoin investors should assess DXY alongside US two year yields and broader risk behavior.
2. Open interest is participation, not direction. Greater altcoin activity can support a broadening market, but it can also represent hedging, short exposure or unstable leverage. The missing dataset limits confidence.
3. The long term thesis and short term trade are different. Institutional adoption may strengthen selected network fundamentals over time, while near term prices remain exposed to CPI, oil, yields and foreign exchange volatility.
We are cautiously constructive on the possibility of wider institutional use, but the immediate setup does not justify certainty that Bitcoin has formed a final bottom. The source itself remains on the fence. In our view, coherent confirmation across currency, bond and risk markets would carry more weight than any isolated move.
Bigger picture
The verified AllinCrypto context points to a market in which crypto is increasingly tied to conventional finance. Bitcoin and Ethereum ETN access through Hargreaves Lansdown illustrates one route for regulated exposure, while infrastructure projects explore tokenized assets on networks beyond Bitcoin.
This makes the simple “dollar down, crypto up” rule less sufficient. Digital assets now sit at the intersection of monetary policy, collateral conditions, exchange traded access, tokenization and derivatives leverage. A future cycle could therefore include strong protocol specific narratives without producing uniform gains across altcoins.
- Macro layer: The dollar, yields, inflation and energy prices shape liquidity expectations.
- Market layer: Open interest reveals participation while leaving direction and leverage quality unresolved.
- Adoption layer: Institutional projects must be evaluated through documented implementation rather than broad sector narratives.
Bitcoin macro outlook FAQ
Why can yen intervention weaken the dollar?
Buying the Japanese yen with reserve assets can strengthen the yen against the US dollar. The transcript attributes the observed currency weakness to this process, although it does not provide a primary official document.
Why do US two year yields matter for Bitcoin?
They reflect market expectations around near term monetary policy. Rising yields can indicate that restrictive financial conditions remain a concern even when the dollar is falling, making the Bitcoin macro outlook less straightforward.
Does higher altcoin open interest confirm an altcoin season?
No. Open interest counts outstanding derivatives positions but does not reveal their direction, quality or concentration. Confirmation would require underlying venue and asset data as well as evidence of sustained demand beyond leverage.
Could institutional adoption favor altcoins over Bitcoin?
Selected networks may benefit when institutions use them for settlement, tokenization or other infrastructure. That possibility is protocol specific, and adoption does not automatically translate into token value or a market wide rally.
What would make the outlook more constructive?
A more consistent combination of dollar weakness, easing yields and improving risk appetite would strengthen the case. Clearer derivatives data and documented institutional activity would also make the altcoin thesis more credible.
Sources
- Something’s Not Right! Dollar Down, Risk Down, Yields Up? Yen Intervention! Alt Vs BTC Open Interst!, YouTube source transcript.
This article is for informational purposes only and does not constitute financial advice.